Quick Answer
There is no such thing as an insurance-approved contractor, at least not as a formal credential. No licensing board, trade association, or insurance company issues that designation. What the phrase actually describes is a contractor who can read an approved scope of work and rebuild to it accurately. Octagon Construction & Energy handles insurance reconstruction across Maine and New Hampshire, rebuilding to the scope your carrier has approved.
What you are usually being told
After a fire, a burst pipe, or a storm that opened up your roof, someone tells you to find an insurance-approved contractor. It might be your adjuster. It might be a neighbor who went through it two winters ago. It might be a search result.
The advice is well meant, and the phrase sounds like it means something specific. It does not. There is no register to check and no badge to look for. What the person is really telling you is: find a reconstruction contractor who has done insured work before and will not create problems with your claim.
That is genuinely good advice. It is just wearing a misleading name.
What an approved scope of work actually is
When your insurance claim is processed, someone produces a document listing what will be repaired or replaced and what the carrier will pay for it. That document is the scope of work.
It is specific. It says how many square feet of drywall, which rooms get new flooring, whether cabinetry is repaired or replaced, whether insulation comes out. It is the actual instruction set for your rebuild.
The scope is real, and it is what everything else depends on. The credential is imaginary. Once you know that, the question changes from “is this contractor approved?” to “can this contractor build exactly what this document says?”
Who creates it
Your insurance carrier’s adjuster produces the scope, or reviews and approves one submitted to them. Some homeowners also hire a public adjuster to work on their behalf during that process.
Either way, this is claim work, and it sits with the adjuster. A contractor’s role begins after that document exists. Octagon Construction & Energy does not produce, negotiate, or influence the scope, and coverage decisions rest with your carrier.
A contractor can, however, prepare construction-related estimate information if your carrier asks for it before the rebuild is finalized. That is not the same thing as negotiating a claim, and it is worth understanding the difference before someone offers you the first as though it were the second.
What the scope covers
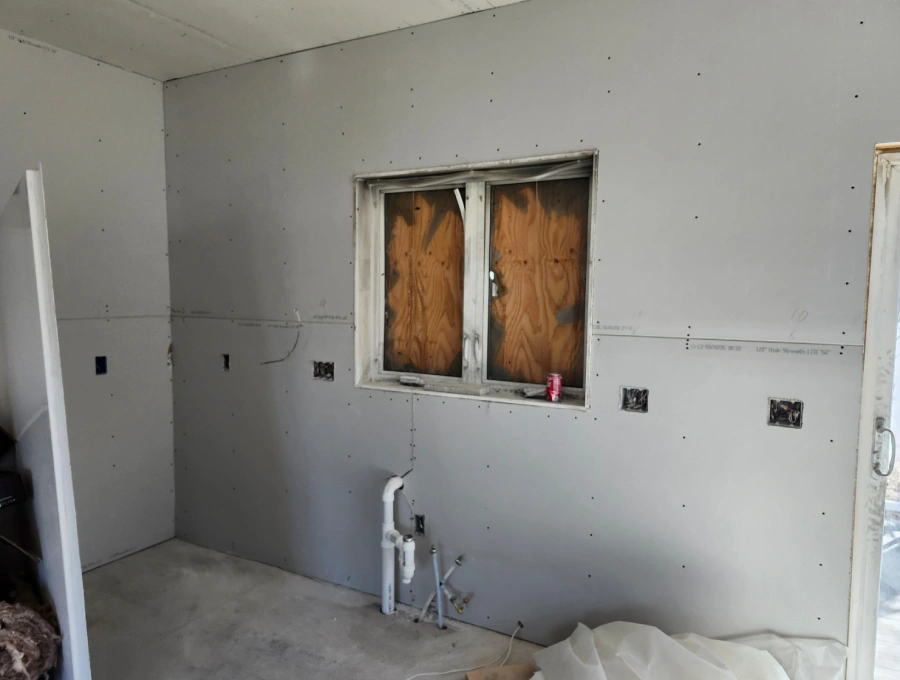
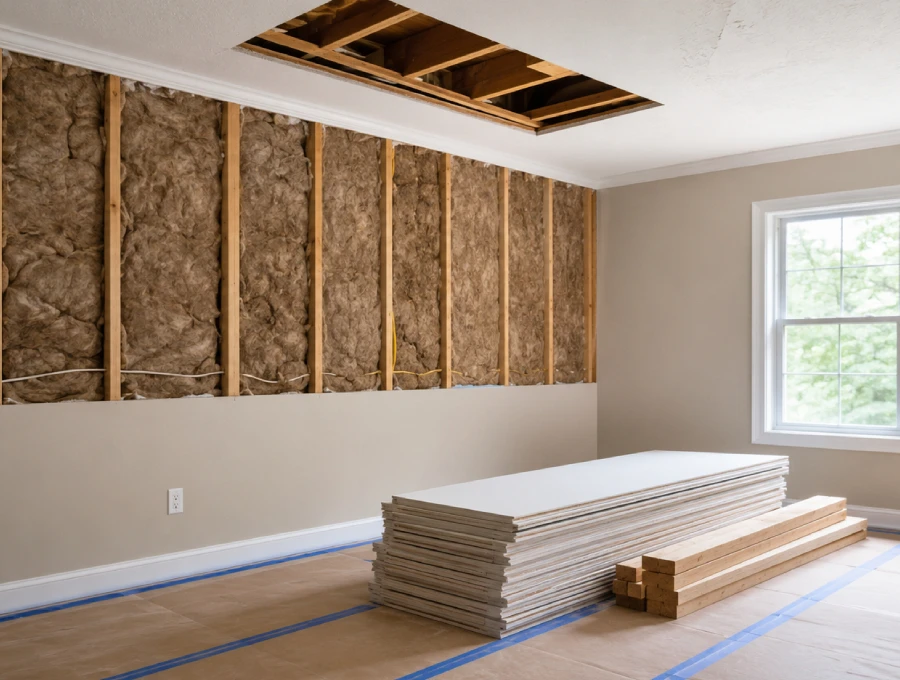
The scope reflects the damage. After a burst pipe or a slow leak, water damage reconstruction typically covers subfloor, insulation, drywall, flooring and trim. After a fire, fire damage reconstruction usually extends further — framing, cabinetry, and the water damage the firefighting itself caused.
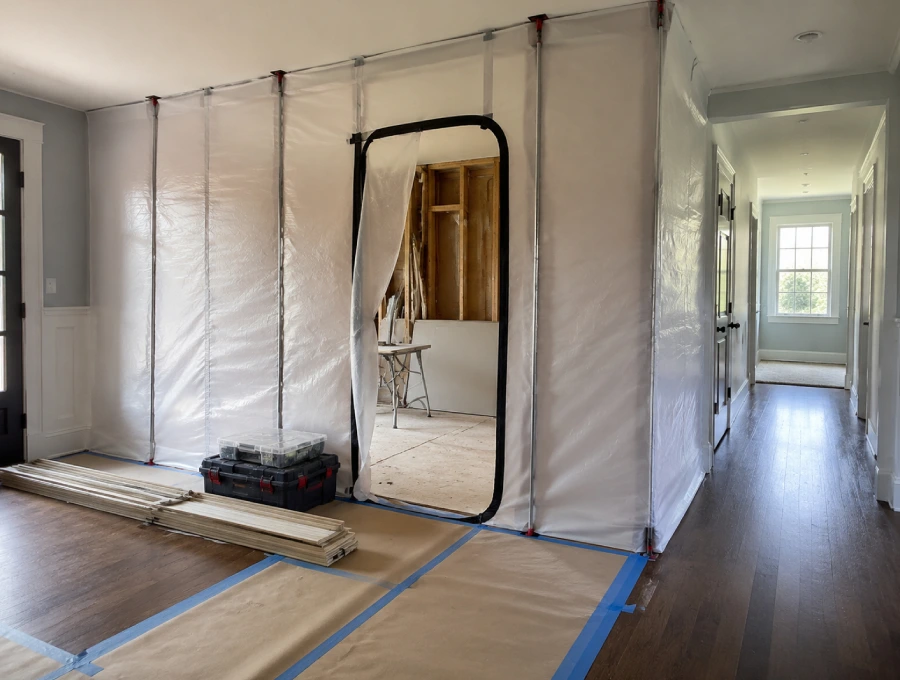
In both cases, the cleanup phase comes first and is carried out by a separate cleaning or mitigation company. Reconstruction begins once the property has been dried, cleaned and stabilized, and the approved scope is in place.
Knowing which phase you are in tells you which kind of company you are looking for. A homeowner still standing in three inches of water needs an extraction crew. A homeowner looking at exposed studs and a signed scope needs a builder.
Questions worth asking instead
Since the credential does not exist, here is what actually tells you whether a contractor can handle an insured rebuild.
Have you worked from an approved scope of work before? Experience with the document itself matters more than any claim of approval. Ask them to describe how they handle a scope that turns out to be incomplete once walls are open.
Are you fully insured, and can you confirm that in writing? This is a legitimate question with a verifiable answer. Octagon Construction & Energy is fully insured.
What happens if you find damage the scope did not include? The right answer involves documenting it and going back to the carrier. The wrong answer involves building it anyway and sorting out payment later.
Do you provide a workmanship warranty? This covers the quality of the labor, separate from any manufacturer warranty on materials. Octagon Construction & Energy provides a one-year workmanship warranty.
Who will actually be on site? Worth asking of any contractor, insured work or not.
What "working to an approved scope" means in practice
It means the rebuild matches the document. Same materials, same rooms, same quantities.
That sounds obvious, and it is where most insured rebuilds go wrong. When work drifts from the scope — a different flooring product, an extra room, a substitution that seemed reasonable at the time — the gap surfaces later as a payment dispute, and the homeowner is usually the one holding it.
A contractor who takes the scope seriously will tell you when something in it does not match what is actually behind the wall, and will document the difference rather than quietly build around it. That habit is what people are reaching for when they say “insurance-approved.” It just has nothing to do with approval.
Frequently asked questions
Is there such a thing as an insurance-approved contractor?
The phrase describes a contractor who can rebuild to the scope a carrier has approved for a specific claim. It is not a formal credential — no licensing body, trade association, or insurance company issues that designation.
What is an insurance scope of work?
It is the document listing what will be repaired or replaced after a claim, and what the carrier will pay for it. It specifies materials, quantities and rooms, and it is what the rebuild is measured against.
Who creates the scope of work after a claim?
Your carrier’s adjuster produces it or approves one submitted to them. Some homeowners also work with a public adjuster during that process.
Does Octagon Construction & Energy negotiate my insurance claim?
Octagon Construction & Energy rebuilds to the scope your carrier has approved, once that scope is in place. Your adjuster handles the claim itself, and coverage decisions rest with your carrier.
What if the contractor finds damage the scope did not include?
It should be documented and raised with the carrier before that work goes ahead. Building outside the approved scope and resolving payment afterwards is how disputes start.